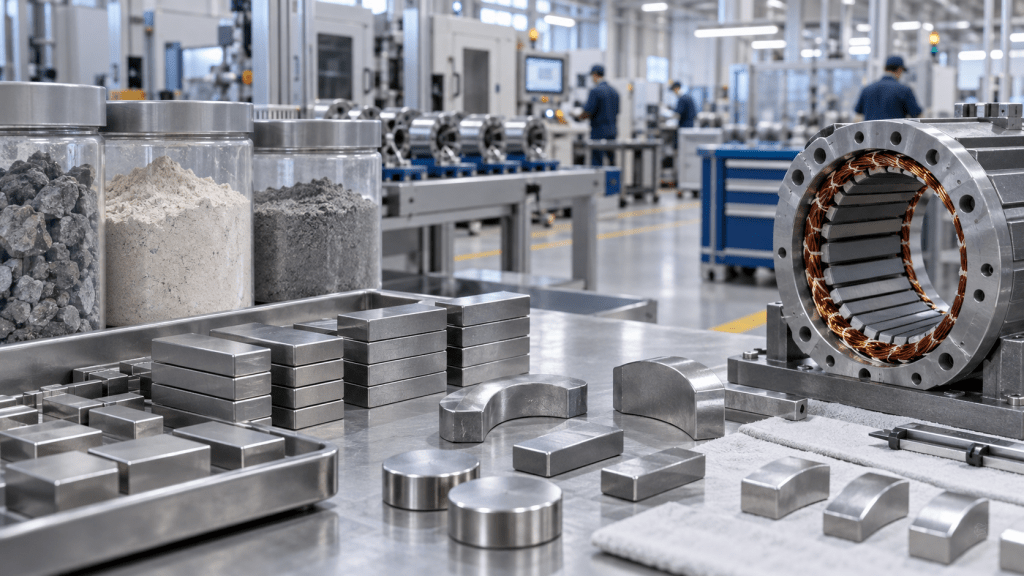
Summary: A September 15 market update described stable NdFeB blank prices but uneven operating rates across downstream applications. Main-drive motor activity improved, while softer industrial-motor demand and limited export recovery kept the overall magnet market moderate.
NdFeB prices held steady while demand signals diverged
Shanghai Metals Market reported that prices for several NdFeB blank grades were broadly stable on September 15, supported by relatively steady rare-earth raw-material prices. The report did not describe a broad demand recovery. Instead, it pointed to different operating trends across end-use sectors.
According to the update, operating rates at major traction-motor producers had improved, but this was not enough to offset weaker industrial-motor activity. Export recovery was also described as limited. The combined picture was a magnet market that remained active but cautious rather than one moving rapidly in either direction.
Raw-material stability does not remove procurement risk
The same report characterized Pr-Nd oxide and alloy markets as largely stable, with limited trading momentum. Dysprosium was steady and terbium’s earlier decline paused, while many buyers remained reluctant to accept higher offers. Recycled NdFeB feedstock also stayed quiet as sellers resisted low bids and qualified scrap supply remained limited.
For buyers of finished magnets, stable daily assessments do not mean every quotation will remain unchanged. A custom NdFeB price also depends on grade, heavy-rare-earth content, coating, machining loss, tolerance, magnetization, testing, order volume and delivery terms. Suppliers may therefore quote different validity periods even when headline oxide prices are flat.
Application mix matters for magnet suppliers
Traction motors and industrial motors do not create identical magnet demand. Electric-vehicle drive systems often require high coercivity, tight magnetic consistency and demanding thermal validation. Industrial motors cover a wider range of duties, sizes and efficiency targets. A rise in one segment can be partially offset by weaker production in another.
This matters for capacity planning. Magnet manufacturers should avoid treating one downstream indicator as a complete forecast. Order intake by application, production lead times and customer inventory policies provide a better view than a single price series alone.
What B2B buyers can do now
Procurement teams can use a balanced market to update quotations and confirm manufacturing slots without assuming that current conditions will persist. Requests for quotation should specify the drawing revision, magnetic grade, coating, magnetization direction, test method, annual volume and required delivery schedule.
Engineering teams should also review whether every part truly needs a high-temperature grade containing dysprosium or terbium. Any material change requires validation, but right-sizing the specification can reduce cost exposure and improve sourcing flexibility. Where dual sourcing is practical, both suppliers should be qualified against the same measurement method and acceptance limits.
A moderate market favors disciplined sourcing
The September 15 update suggests stability without strong momentum. Traction-motor activity offered some support, while industrial demand and exports remained less robust. Buyers should treat the report as a market snapshot, obtain current written quotations and connect purchase timing to actual production requirements rather than to short-term price headlines.